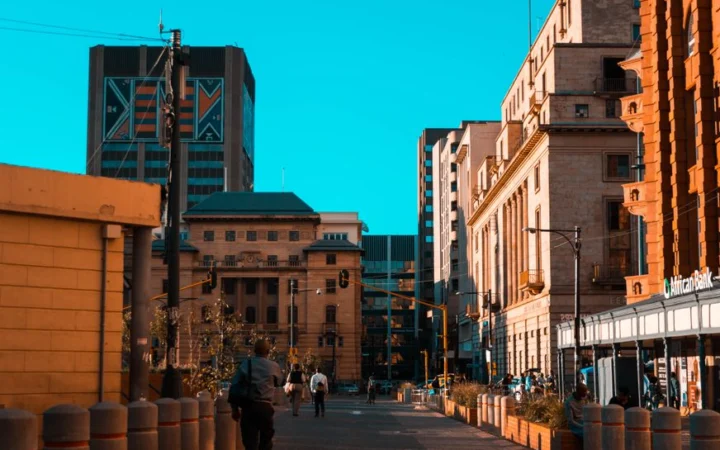
Empty office towers in Manhattan look nothing like the bustling distribution hubs lining Texas highways. British capital flows heavily into US commercial real estate, but choosing the wrong asset class burns cash fast. Post-pandemic shifts altered everything. Remote work battered urban office towers. E-commerce fueled massive demand for suburban warehouses. You need to know where returns actually live.
The Reality of US Commercial Real Estate Today
Interest rates from the Federal Reserve changed the math entirely. Cheap debt vanished overnight. Property valuations dropped across multiple sectors. Yet, not every corner of the market suffers equally. Retail holds steady in grocery-anchored strips. Multifamily housing remains resilient despite supply spikes in the Sun Belt. But the real battleground sits between downtown office blocks and massive industrial distribution sheds.
UK institutional funds and private family offices face a stark choice. Do you chase discounted downtown office assets offering high cap rates, or do you pay a premium for logistics hubs leased to tenants like Amazon and FedEx? The answer depends entirely on your risk tolerance and holding period.
Why Industrial Logistics Parks Dominate US Commercial Real Estate
Supply chains changed permanently over the last five years. Companies keep more inventory on hand now. Just-in-time delivery proved too fragile during global disruptions. This behavioral shift created a massive structural tailwind for industrial assets within the broader US commercial real estate market.
Vacancy rates for prime logistics space in markets like Inland Empire, Chicago, and Atlanta hovered near historic lows for years. Rents climbed double digits annually through the early 2020s. Even as new construction cools down due to higher borrowing costs, tenant demand persists.
Leases here usually run triple-net. Tenants pay property taxes, insurance, and maintenance costs directly. That means predictable cash flow for a landlord based in London. Cap rates sit lower than offices, but the income stability draws conservative capital.
The Case for Bargain-Priced US Office Assets
Office buildings look broken on paper. Headlines trumpet plummeting valuations in San Francisco, Chicago, and New York. Return-to-office mandates stumble against employee resistance. Lenders face mounting pressure as commercial mortgage-backed securities mature.
Distress creates opportunity for bold buyers. Class-A towers in prime submarkets trade at steep discounts to replacement cost. Some foreign buyers scoop up trophy assets for pennies on the dollar, planning multi-million dollar upgrades to attract tenants back with high-end amenities, wellness centers, and collaborative spaces.
Class-B and Class-C offices face a much darker future. Many will never recover their previous occupancy levels. Converting them into residential apartments sounds clever in theory, but zoning laws and structural costs make it financially prohibitive in most US cities.
Financing and Cross-Border Hurdles for British Buyers
Buying property across the Atlantic requires navigating complex legal structures. US lenders require substantial equity contributions today. Loan-to-value ratios rarely exceed fifty or sixty percent for office deals. Industrial assets command slightly better debt terms because banks view them as safer collateral.
Structuring ownership matters. Most foreign investors use US corporate holding structures or real estate investment trusts to manage tax exposure. You must factor in federal withholding taxes, state-level property taxes, and local municipal fees before projecting net yields.
Currency risk adds another layer of complexity. Sterling fluctuations against the US dollar can wipe out a year of rental gains. Hedging currency exposure eats into returns, but skipping it exposes your portfolio to wild macroeconomic swings.
Final Verdict for British Capital
Industrial logistics wins this comparison for most UK investors. The fundamentals remain strong. Tenant demand holds firm. Maintenance capital expenditures stay relatively low compared to aging office towers.
Office assets suit opportunistic private equity funds with deep pockets and local operating partners. They are not suitable for passive investors seeking stable quarterly distributions. If you want exposure to US commercial real estate without the headache of urban vacancies, stick to modern logistics parks near major ports and transport corridors.
For more information, visit our website.
Learn more on Wikipedia: US Commercial Real Estate Index.
Related reading
- How to Track US Natural Gas Storage Reports from the UK
- US Inflation Data and the Federal Reserve: What British Investors Need to Know
Update: Decoding US Interest Rates: Why American Monetary Policy Drives British Borrowing Costs
Update: US Corporate Tax Rates: What British Owners Need to Know